Autocorrelation
Definition
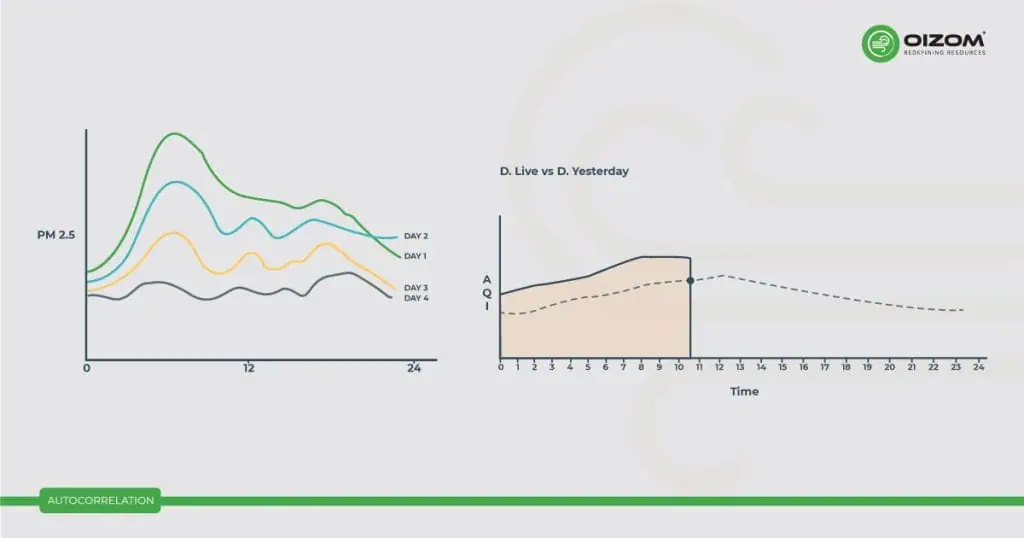
Autocorrelation, also known as serial correlation, is a statistical concept that measures the degree to which a time series or a signal is correlated with a lagged version of itself. In other words, it assesses the correlation between data points at different time intervals within the same series. When autocorrelation is high at a specific lag, it indicates a repeating pattern or relationship between data points separated by that time lag. Autocorrelation is often used in time series analysis to identify trends, seasonality, or periodic patterns in data. It is a valuable tool in fields such as statistics, signal processing, and econometrics for understanding and modeling temporal dependencies in data.